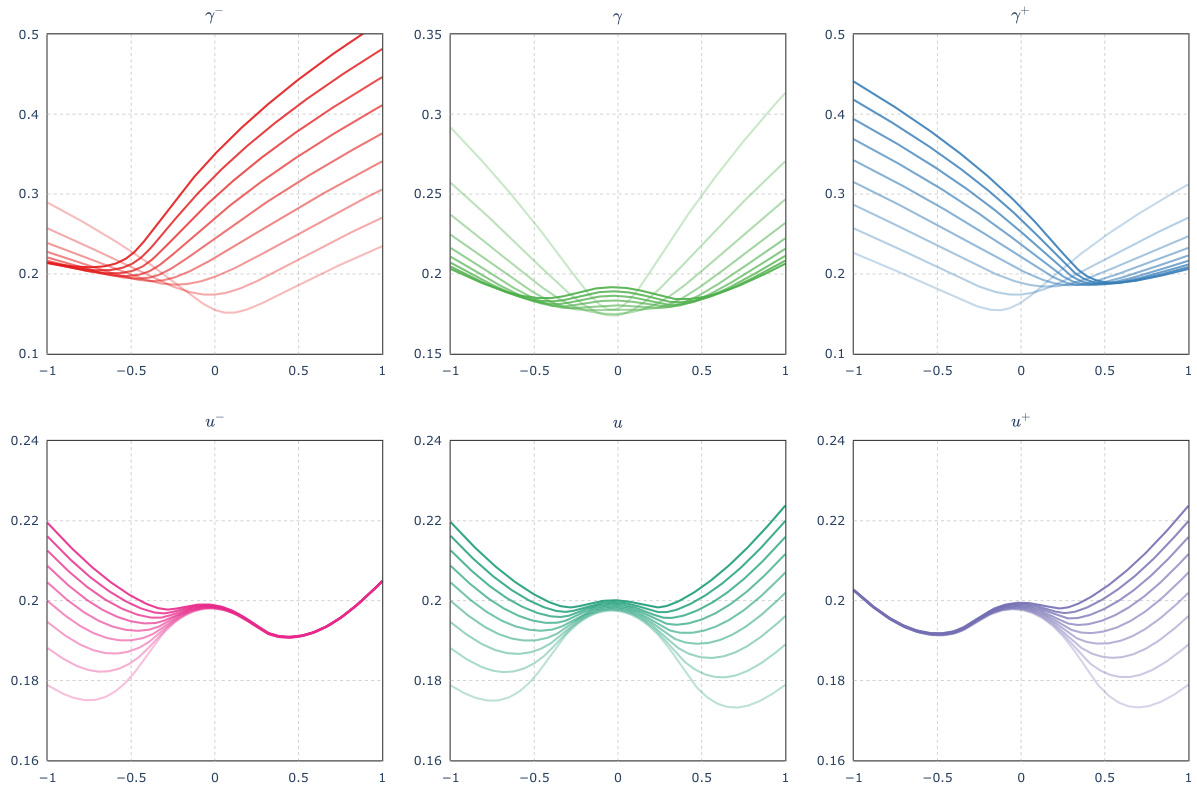
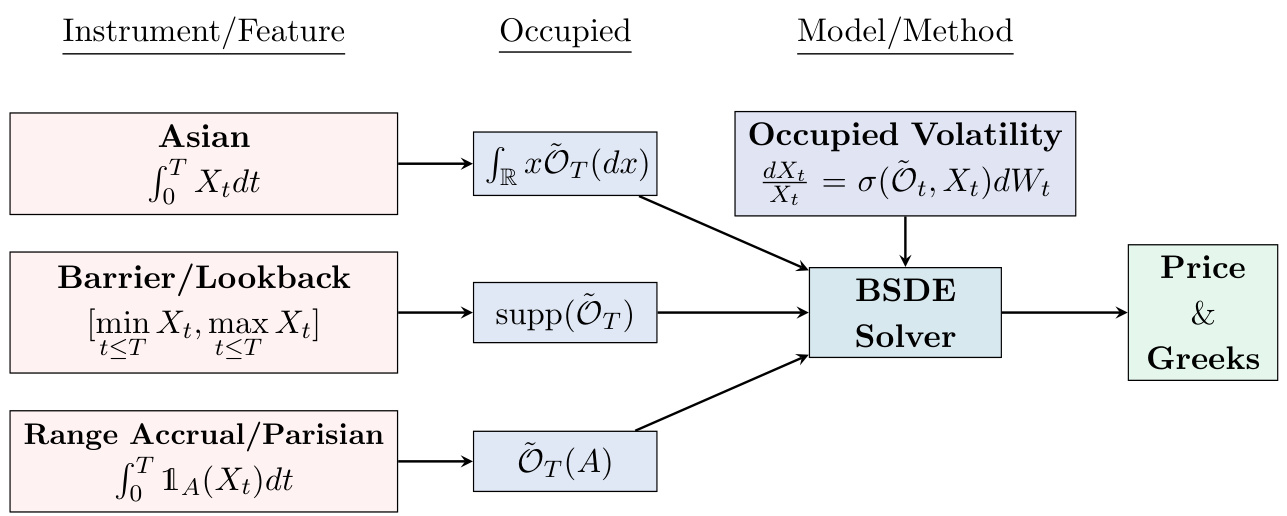
本研究提出并分析圆柱投影法,将占用流从无限维的状态空间投影到可控的有限维系统,保留路径依赖的关键信息。作者给出强收敛性与收敛速率,给出 Euler–Maruyama 离散化的实现方案,并在 Cranston–Le Jan 自吸引扩散以及局部占用波动 LOV 模型等金融应用中验证数值性能。还给出弱误差分析及其对 Monte Carlo 估计与期权定价的影响,为路径相关的金融模型提供一类通用且可控的数值工具
One Other Option Pricing Scheme
发表于 2026年7月27日上传于 2026年7月28日
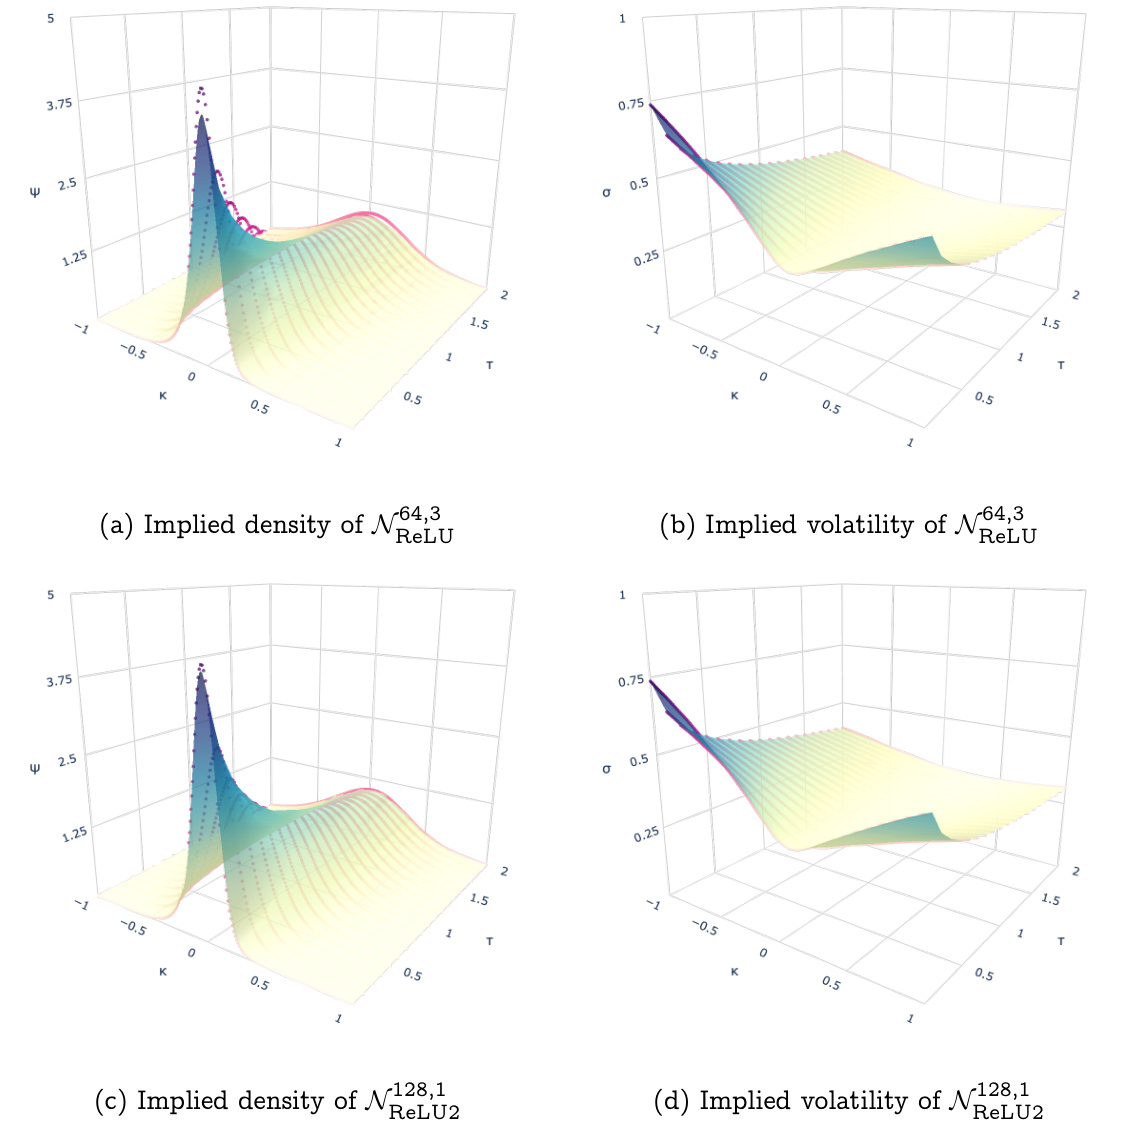
This paper introduces a parsimonious and interpretable framework that directly parameterizes the risk-neutral quantile function to control the shape of the implied volatility curve, including local concavity and non-convex shapes observed in modern markets. The approach calibrates across a quarter million implied volatility curves over the past two years, producing stable parameter patterns across tenors and moneynesses that enable term-structure interpolation and dynamic process construction without static arbitrage. These results demonstrate strong empirical performance and practical tractability for a broad set of market conditions .
Bid–Ask Martingale Optimal Transport
发表于 2026年3月27日上传于 2026年3月27日
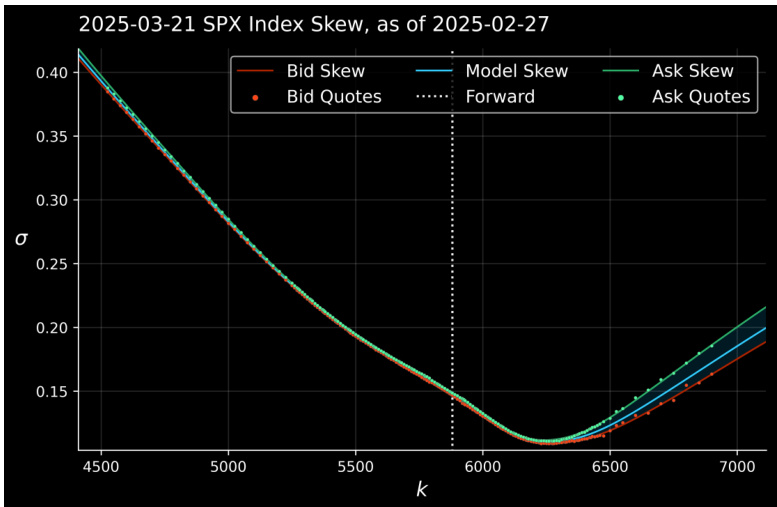
本文提出 Bid–Ask MOT(BAMOT),在经典 Martingale Optimal Transport 框架中引入对期权买卖价差(bid–ask spread)的约束,使模型边际分布仅需位于买卖边际之间的凸序列,从而获得更现实的衍生品稳健价格界与等价的强对偶表述;我们证明了单一到多期的强对偶性并给出当买卖价差收敛为零时 BAMOT 收敛至经典 MOT 的一致性与定量收敛率(线性或平方根速率),并用合成与真实 SPX 数据示例验证方法论与数值影响
Shallow Representation of Option Implied Information