Probability equivalent level for CoVaR and VaR in bivariate Student- $t$ copulas with application to foreign exchange risk monitoring
发表于 2025年9月2日上传于 2025年10月21日
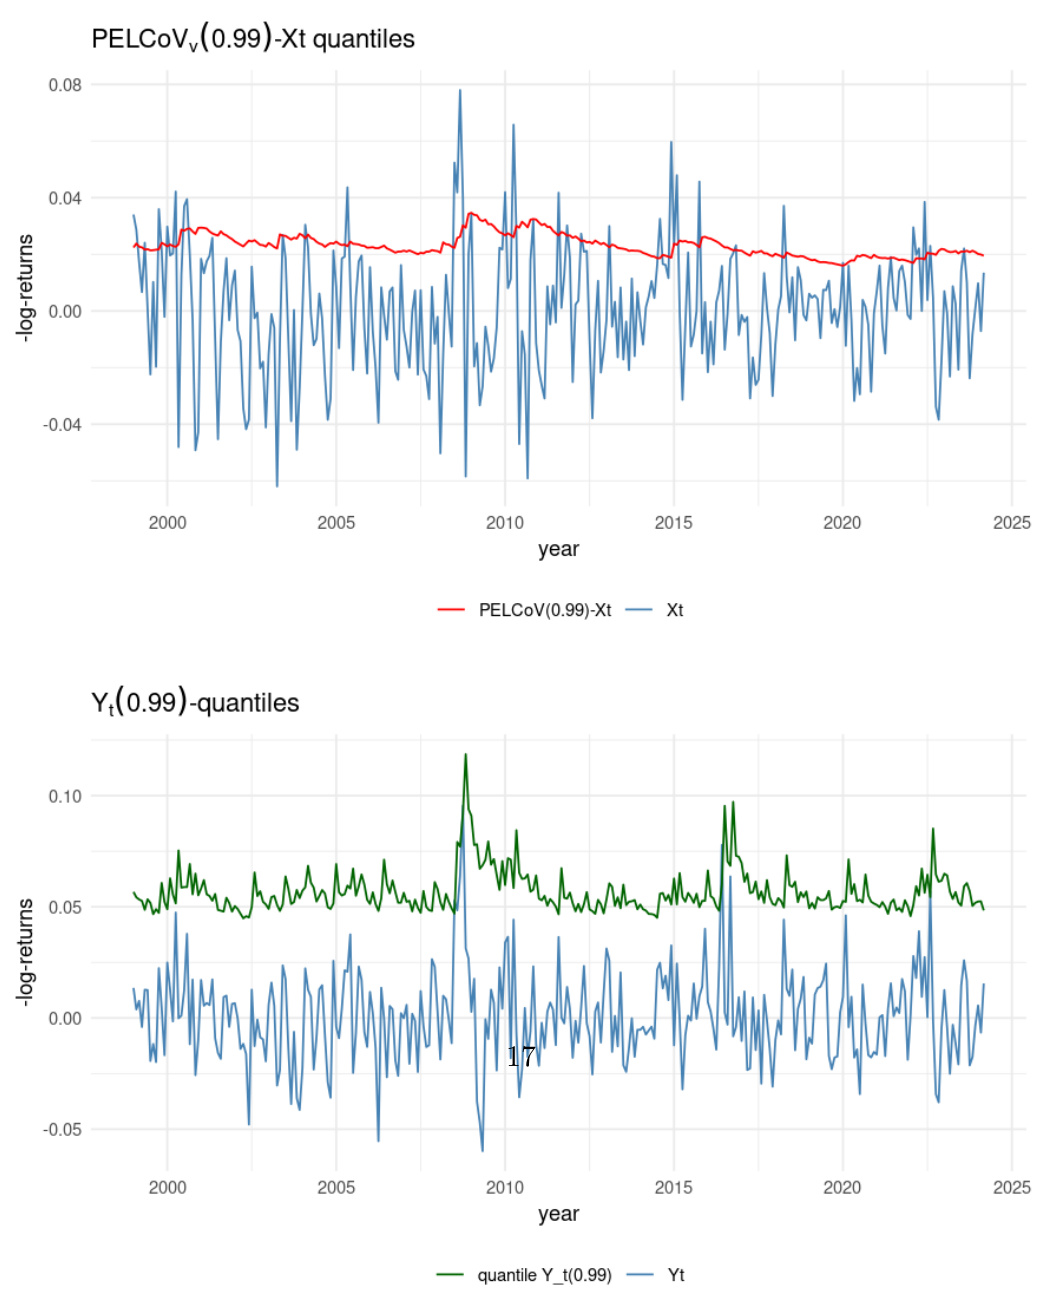
本论文扩展了基于Student-$t$ copula的PELCoV方法,解决了之前依赖强相关假设的局限,动态追踪外汇市场中美元兑英镑和欧元的风险传染关系。实证显示该方法可有效预警极端风险事件,并成功捕捉多个金融波动期的风险。