A Quadratic Link between Out-of-Sample $R^{2}$ and Directional Accuracy
发表于 2026年2月17日上传于 2026年2月17日
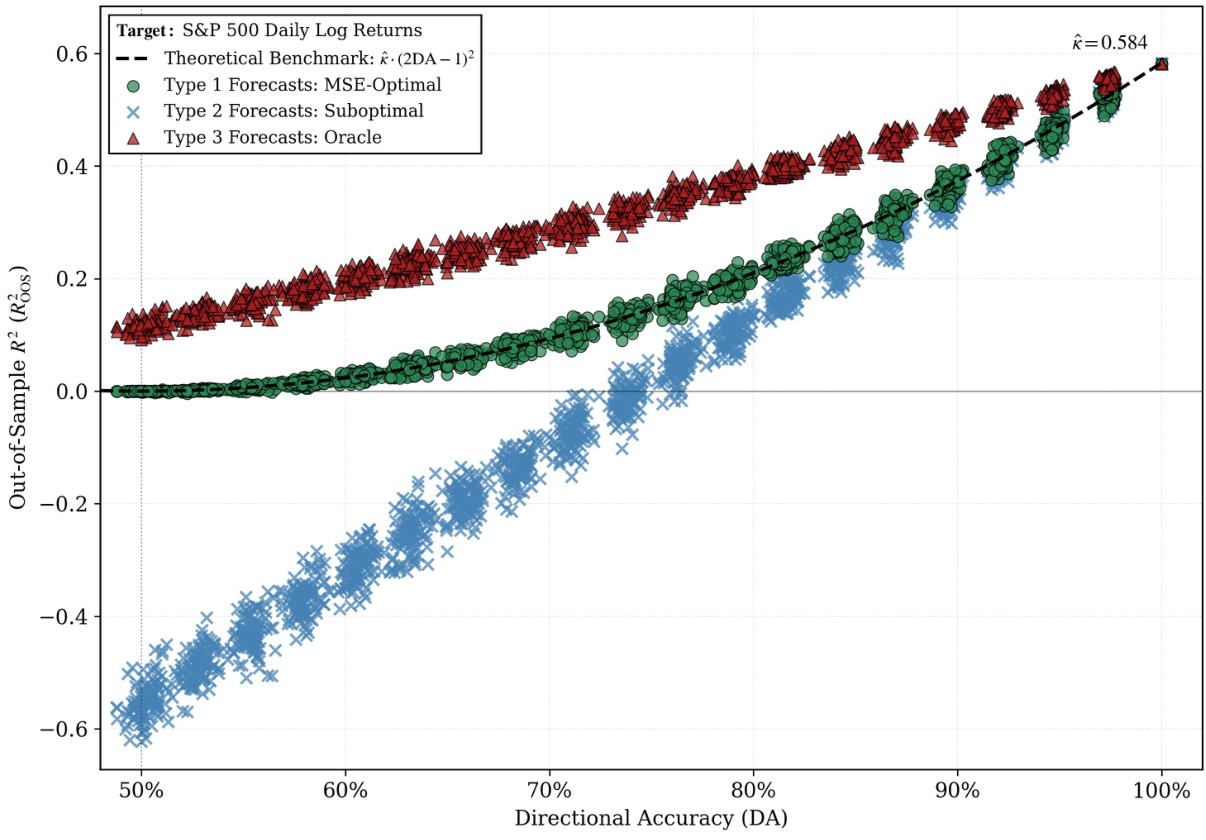
This paper derives an analytical quadratic relationship between out-of-sample R^2 and directional accuracy for MSE-optimal point forecasts, showing that R_OOS^2 = κ(2·DA−1)^2 under mild independence and volatility assumptions; as a result, modest DAs (≈0.55–0.60) imply intrinsically small theoretical R_OOS^2 and negative empirical R_OOS^2 values are expected under suboptimal scaling or finite-sample noise, a finding validated by simulation on S&P500 and DJIA series .