This paper revisits the exchange rate disconnect puzzle using generative AI to forecast currency returns from economic fundamentals. Employing ChatGPT and DeepSeek, a comprehensive dataset of 544 indicators spanning 1996–2024 is analyzed to extract AI-derived fundamentals, showing significant cross-sectional predictability across major currencies. A simple AI-driven AIFX strategy—going long currencies with strong fundamentals and short those with weak fundamentals—achieves an annualized Sharpe ratio above 0.7, with alpha that remains significant after controlling for standard FX factors. Multiple robustness checks (GPT-4o and DeepSeek-V3, weighted signals, and time-series specs) support the central results. Four look-ahead bias tests indicate the results arise from AI reasoning rather than memorization, and the Taylor-rule framework linking fundamentals to monetary policy emerges as a key mechanism behind the predictability.
FinSMART: Financial Sentiment Analysis for Algorithmic Trading through Market-Aligned Reinforcement Learning
发表于 2026年7月30日上传于 2026年7月31日
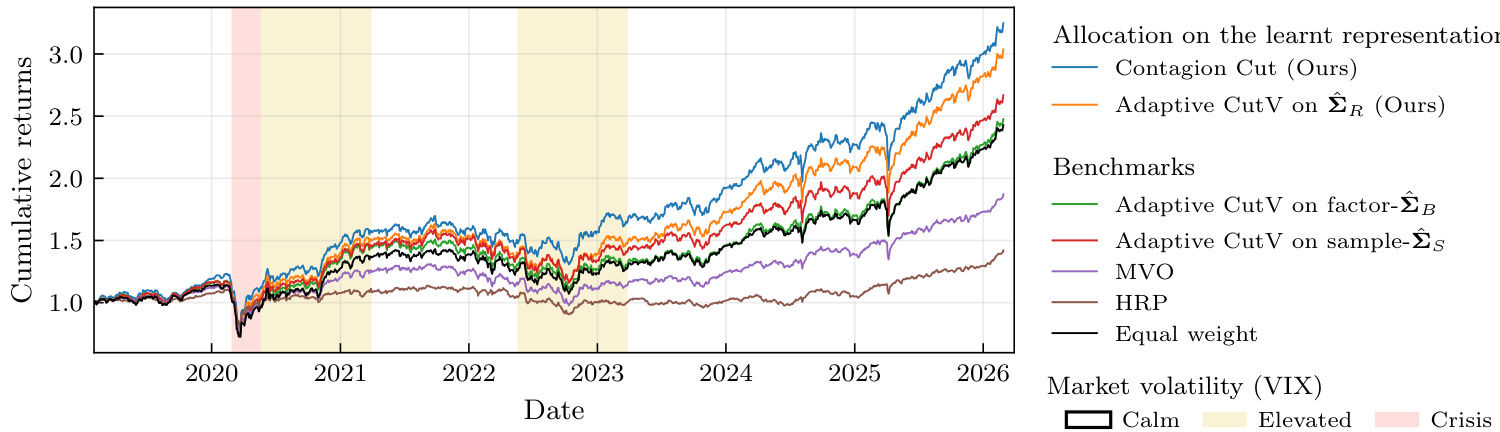
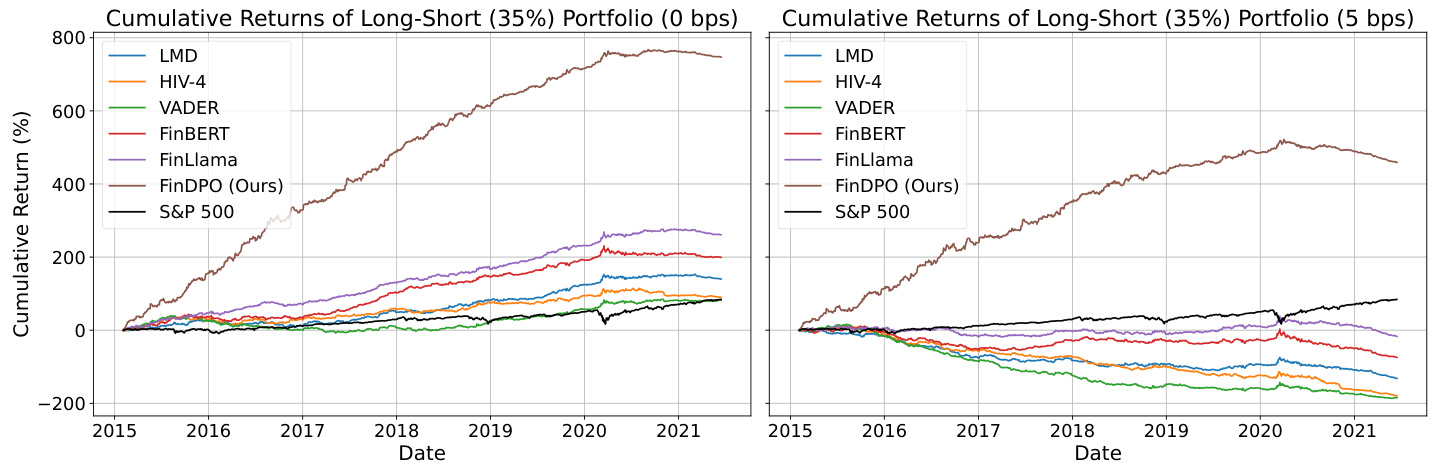
FinSMART introduces a market-aligned reinforcement learning framework for financial sentiment analysis that directly optimizes sentiment signals using realized market outcomes, enabling continual adaptation through market-aware retraining . The approach uses a dual-filter reward with asymmetric incentives and a GRPO optimization to align sentiment with profitable market activity, achieving substantial improvements in profitability, risk-adjusted performance, and signal quality compared with state-of-the-art methods (e.g., FinDPO), including a 220% increase in cumulative trading returns over the strongest baseline and improved RankIC . The framework further demonstrates the practicality of market-aware retraining—replacing costly human labels with observed articles and outcomes to sustain performance gains under evolving market dynamics .
Local Stochastic Rough Volatility: Pathwise Filtering and the Conditional Density Equation