Time Preference and Tax Burden Acceptance: Asymmetric Effects on Intertemporal and Contemporaneous Redistribution
发表于 —上传于 2026年4月20日
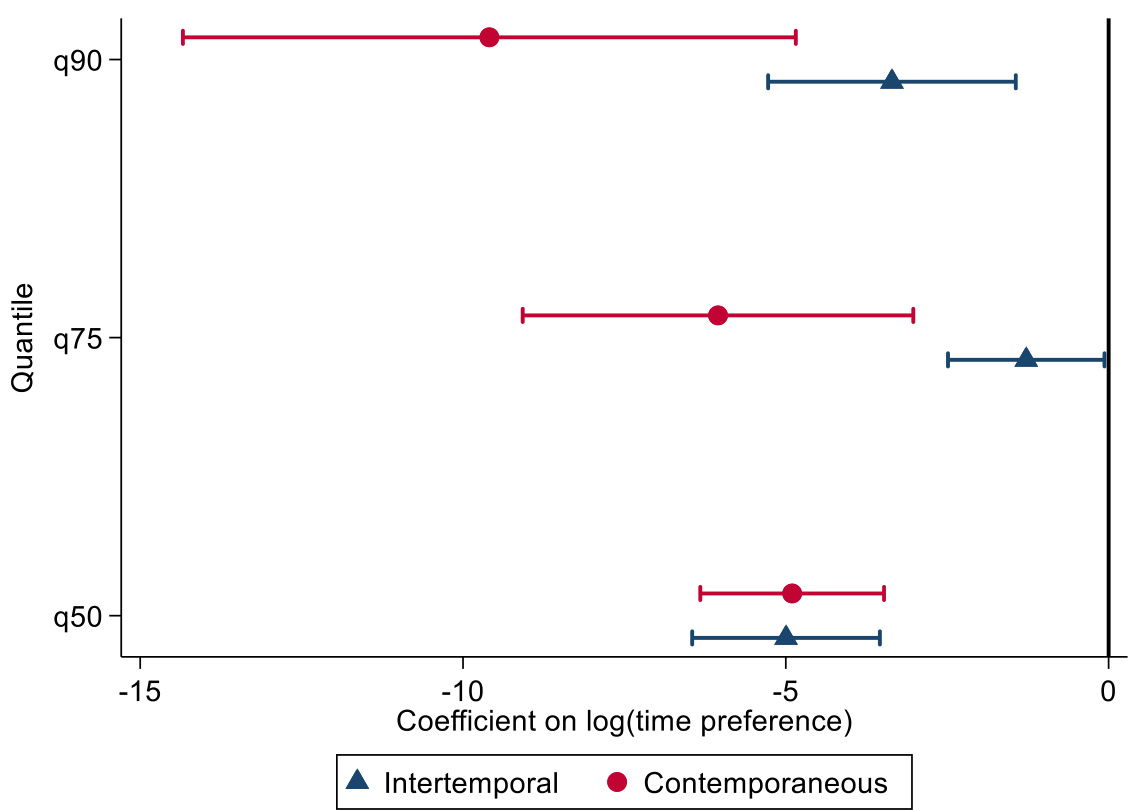
基于约12,000份问卷,本文比较了“当前增税换取未来减税”(跨期再分配)与“当期将税款直接转给低收入者”(同时再分配)两种情景下的可接受最高税率,发现更强的现时偏好(高 time preference)会降低两类再分配的接受度,但对同时再分配的负向影响在绝对值上更大,且这种不对称性在高分位(高接受者)尤为明显 。