The Economic Benefits and Costs of AI and Policies to Mitigate AI’s Impact on Inequality
发表于 2026年7月2日上传于 2026年7月2日
We develop a two-sector, three-labor-type model where AI is produced by labor and used in final goods production, yielding endogenous labor reallocation as AI productivity rises . AI adoption creates a transition in which substitutable labor incomes fall in absolute and relative terms while complementary labor wages rise faster than GDP, and final goods labor tracks GDP one-for-one . The model identifies threshold productivity levels that separate pre-AI, transition, and post-AI regimes; the wage ratio between complementary and substitutable labor depends only on AI productivity and AI-production intensity, not on relative labor supplies . We analyze Pareto-improving tax and regulatory policies that share AI gains across workers, and show how outcomes differ under competitive AI production versus monopoly AI production . The paper also extends to AI-in-AI production and to CES-type AI technologies, confirming robustness of the main qualitative results and highlighting how policy design must adapt as AI productivity evolves .
Double Fuzzy Probabilistic Interval Linguistic Term Sets and a Dynamic Markov Fuzzy Decision-Making Model for Multi-Criteria Group Decision Making: Revised Version
Measuring Racial Disparities in Rent Growth Under Algorithmic Landlord Concentration in U.S. Metros
发表于 2026年6月29日上传于 2026年6月30日
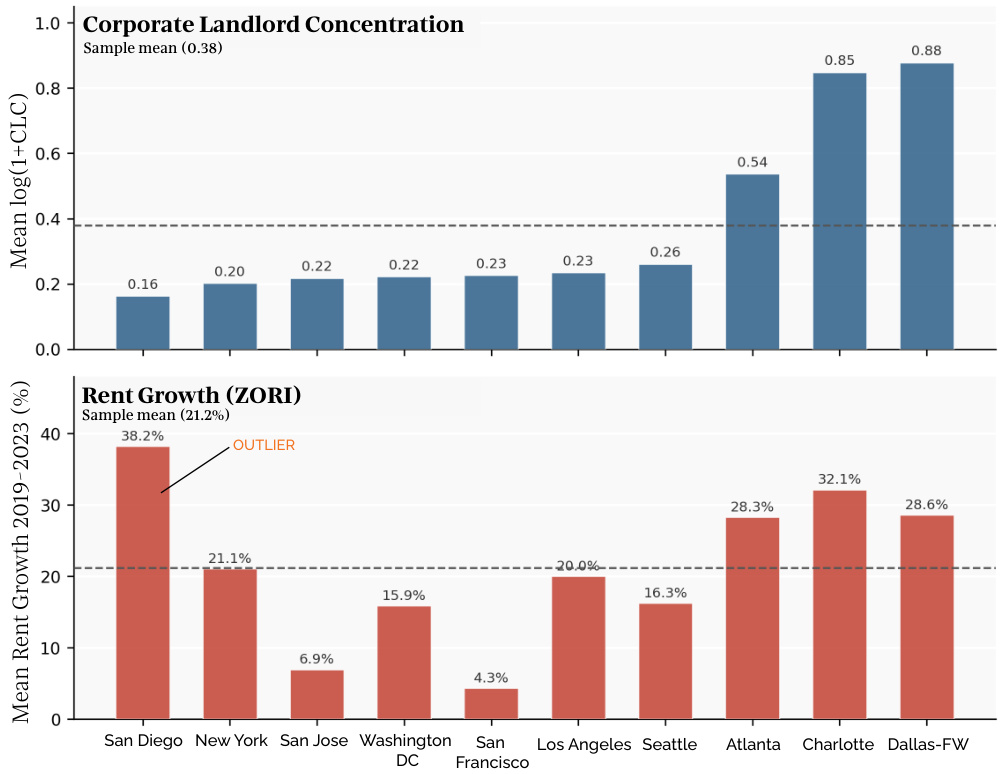
本研究通过把公开监管披露的机构房东集中度(CLC)与Zillow Observed Rent Index (ZORI)租金指数结合,检验2019-2023年间CLC是否与租金增长相关,并考察在多数族裔社区中的异质性。结果显示,CLC翻倍与租金增长约多出2.8个百分点,且在 majority-minority街区的效应显著更强;同一区域内高CLC的 minority街区较白人街区的租金增速更高,差异约为5.9个百分点;以XGBoost预测并结合SHAP分析,CLC对 minority街区的贡献为正、对白人街区为负。本文提出AHBI等新指标,指出ACS 5年估计不足以捕捉短期租金波动,交易性数据如ZORI更具捕捉能力。以上结论在OLS互动、 metro FE、以及非参数的SHAP分析中得到一致性验证,构成对算法化租金定价在有色社区中的分布性影响的首批区级证据
Statistical Arbitrage in Rank Space
发表于 2026年6月29日上传于 2026年6月30日
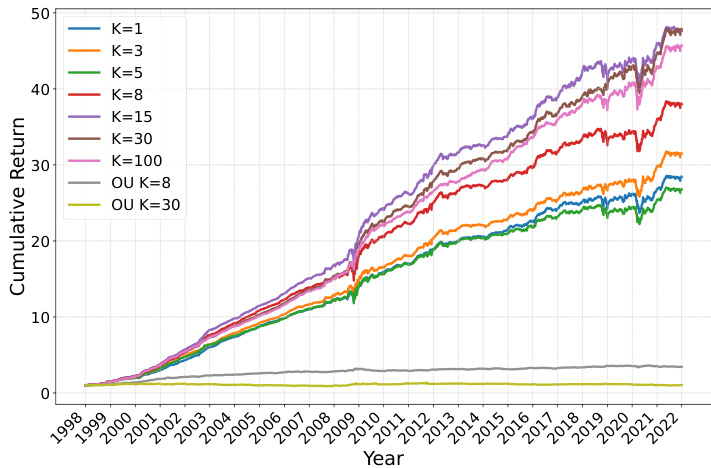
本研究提出将股票以市值排名作为输入表示来进行统计套利,证明在排名空间中使用深度神经网络进行残差投资组合的学习相较于名称空间具有更鲁棒的市场表征与更强的残差均值回归,从而显著提升学习效率与盈利能力。基于美国市场数据,rank space 的 DNN 投资组合在2007-2022年间实现平均年化收益约35.68%、夏普比率约3.28(扣除交易成本2bp),显著领先名称空间的结果。该研究还显示在排序空间中利用灵活杠杆与回撤管理的潜力,以及因交易成本带来的挑战,强调领域知识驱动的数据转换在金融深度学习中的重要性
Chaos and Synchronization in Financial Leverages Dynamics: Modeling Systemic Risk with Coupled Unimodal Maps
发表于 2026年3月31日上传于 2026年3月31日
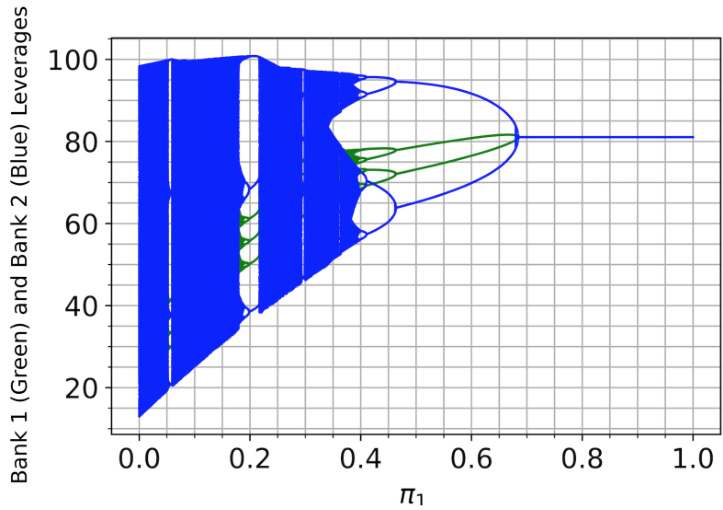
本论文构建并分析了银行杠杆的离散动力学模型:单一银行情形下杠杆由一维单峰映射T支配并随风险记忆参数ω出现倍周期分岔与混沌;在多行者情形下,耦合的单峰映射通过均场项(基于资产权重π)互联,展示了同频化、强制—被强制(big vs small)动力学与类Hénon吸引子等现象,从而阐明了微观杠杆目标化行为如何生成系统性风险的宏观不稳定性
Private Credit Markets Theory, Evidence, and Emerging Frontiers
The Heterogeneous Earnings Impact of Job Loss Across Workers, Establishments, and Markets
发表于 2026年3月17日上传于 2026年3月17日
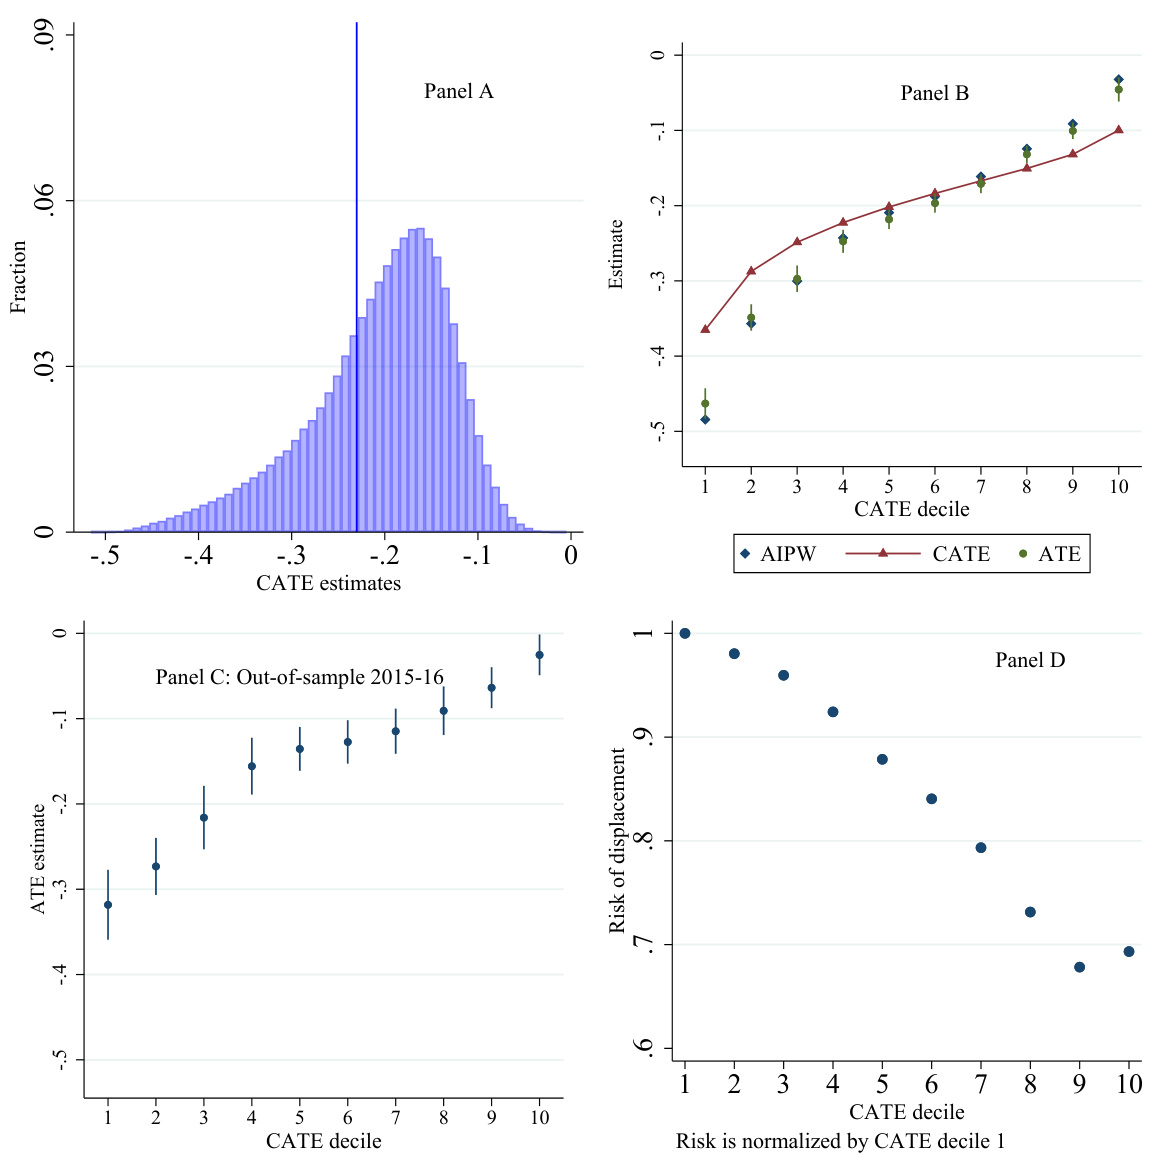
本文利用瑞典行政微观数据和因果机器学习(Generalized Random Forest, GRF)估计就业厂关闭导致的相对年收入损失的条件平均处理效应(CATE),发现跨工人、企业与市场的异质性极大:短期平均收入下降约24%,但最易受冲击的分位组损失接近46%,最韧性组仅约6%,且短期预测对中长期损失具有稳定预测力,表明多维且可操作的定向救助政策(例如基于年龄与岗位例行性规则)能够显著提高救助效率与公平性
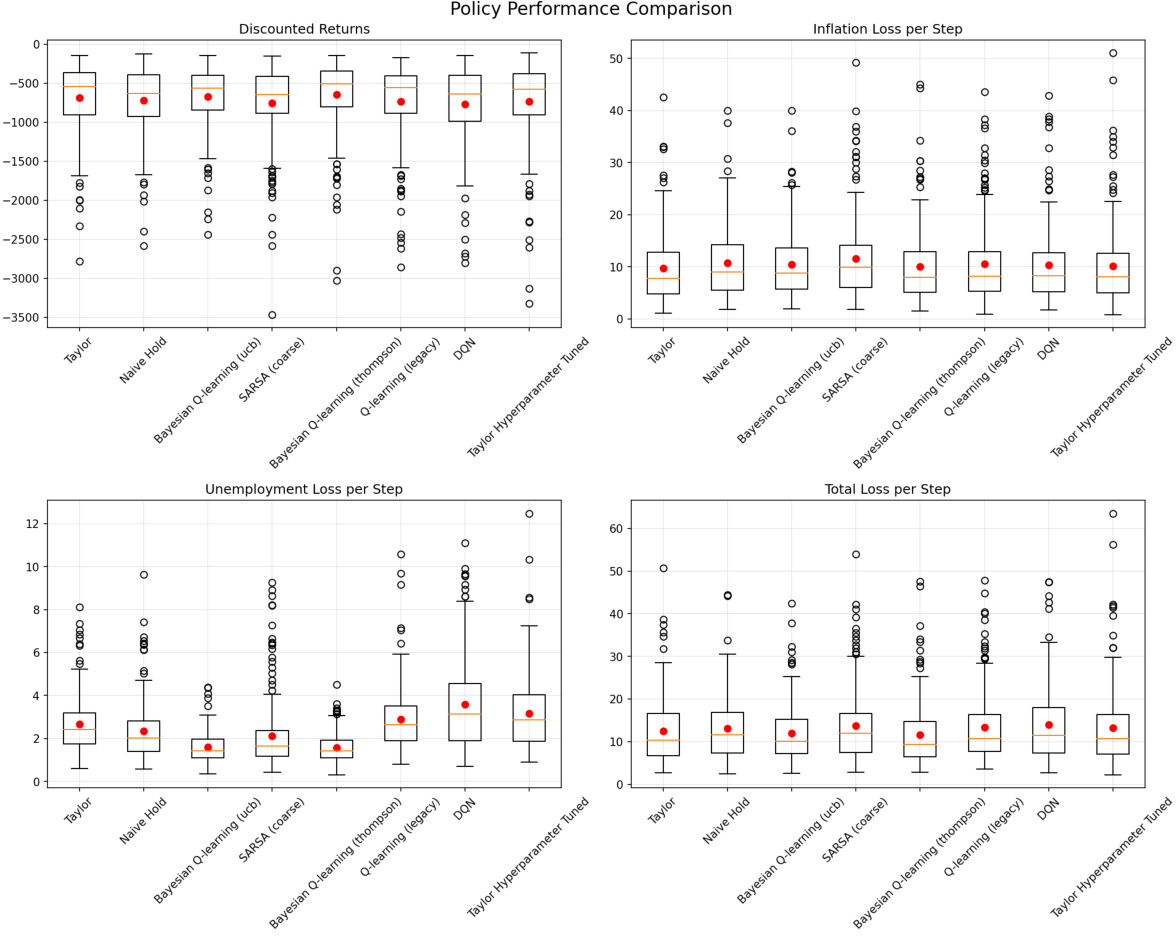
Reinforcement Learning for Monetary Policy Under Macroeconomic Uncertainty: Analyzing Tabular and Function Approximation Methods
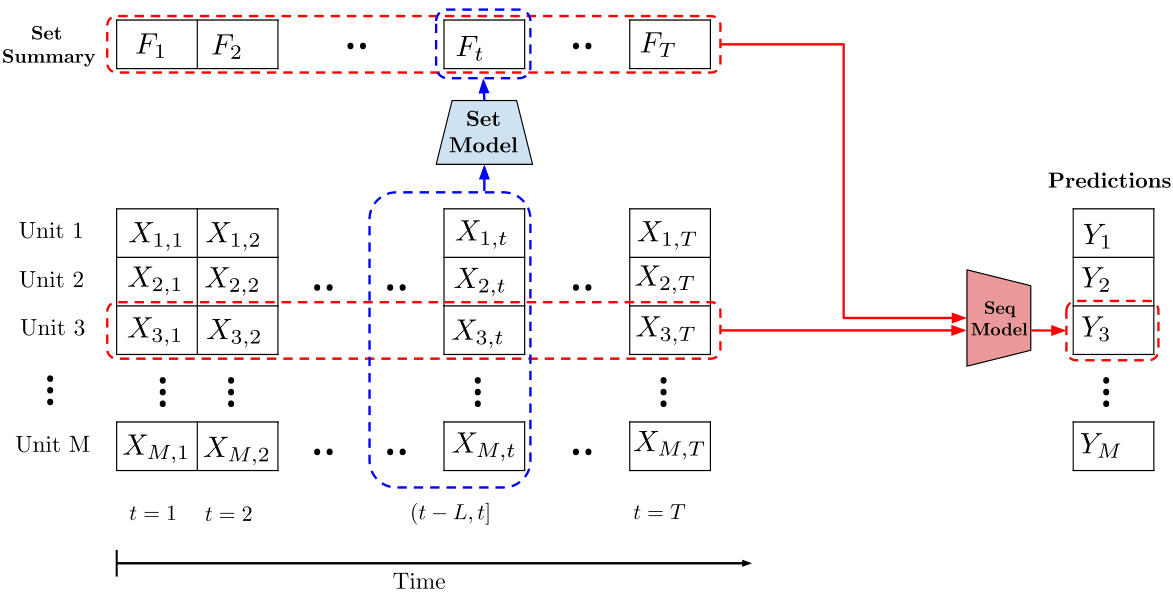
本文提出了Set-Sequence模型,通过在每个时间步引入无序集合( Set )模块学习跨截面潜在依赖,并结合序列( Sequence )模块捕捉时间动态,实现对大规模高维时间序列的高效预测。该模型具备对单位数目变化的适应性,计算复杂度线性缩放,避免了手工设计特征。经过合成信贷传染任务、美股股票组合构建和美国抵押贷款风险预测三类实证检验,Set-Sequence模型显著优于传统序列模型,提高了预测准确率(如AUC提升)、经济性能指标(年化Sharpe比率提升22%),并具备较强解释性,所学的集合摘要紧密追踪潜在风险因子
Attributing excess conflict risk in Syria to anthropogenic climate change