Mapping the causal structure of price formation in Texas’s transitioning electricity market
发表于 2026年4月15日上传于 2026年4月17日
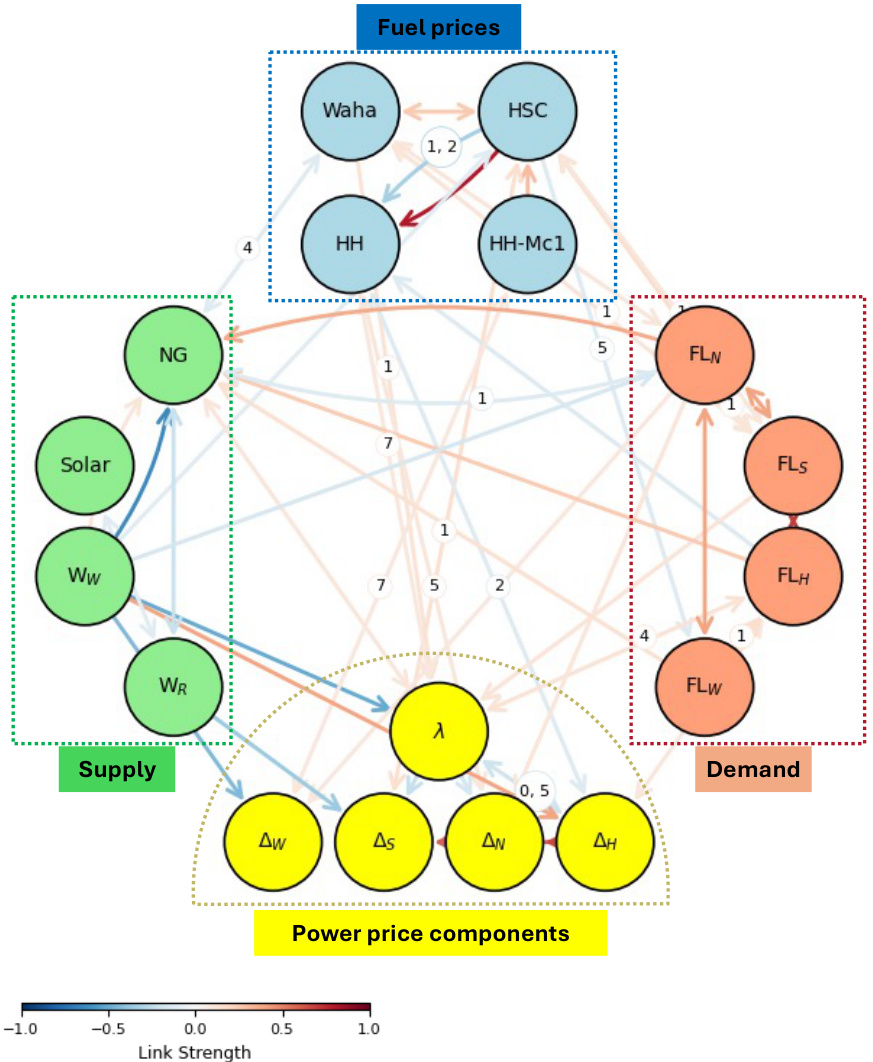
This study applies recent time-series causal discovery (LPCMCI) to ERCOT day-ahead prices (2019–2024), showing West Texas wind forecasts have become the dominant causal driver of the system-wide price (lambda), with effects on average ~3.4x larger than natural gas price effects; these causal relationships vary systematically by season, time-of-day and region, and the dominant gas benchmark shifts from Waha to Henry Hub over the study period .
Factor Engine: A Python Library for Systematic Financial Factor Computation and Analysis
发表于 2025年7月27日上传于 2026年2月17日
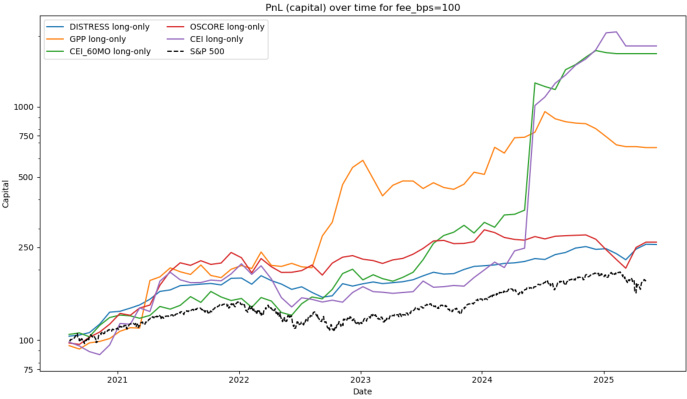
本论文介绍 Factor Engine——一个以可扩展、可复现为设计目标的高性能 Python 因子计算库,采用装饰器 API 简化因子定义与管理,并通过与 Stata 参考实现的相关性与回测比较验证了计算正确性与实用性,为量化因子工程和策略开发提供了实用工具与范式