Reaction-boundary variance and adjoint-consistent local-volatility projection
发表于 2026年7月6日上传于 2026年7月7日
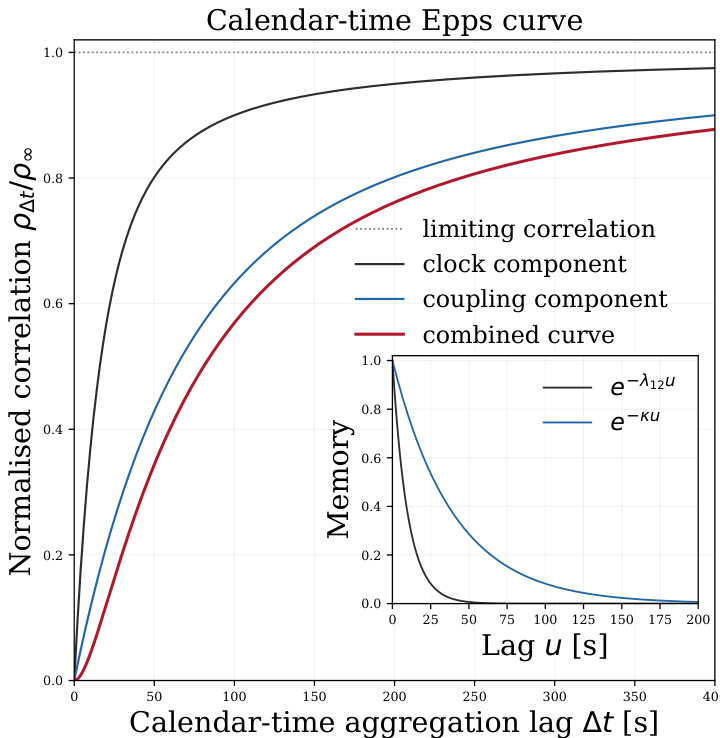
We derive an operational-time variance kernel for a latent-order-book reaction boundary and show how calendar-time local volatility can be obtained via clock projection and pricing-measure choice. The boundary displacement arises from a damped Abel response to signed order-flow, with the variance realized as a finite-scale cumulant rather than a primitive diffusion coefficient. A deterministic activity clock yields a benchmark projection, while non-unique clocks move incompleteness to the projection layer; adjoint consistency provides a reality constraint ensuring coherent pricing across calendar time .
A Monotone Limit Approach to Entropy-Regularized American Options
发表于 2026年2月23日上传于 2026年2月23日
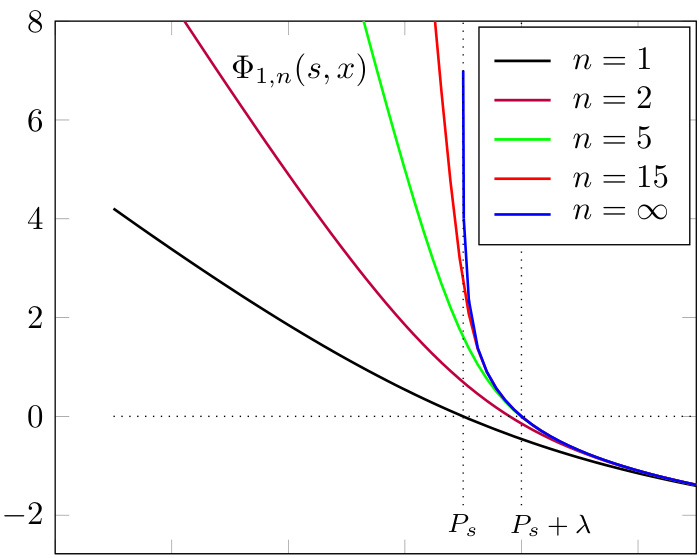
本文提出一种基于Doob–Meyer–Mertens分解与反射型BSDE的纯概率框架,通过引入修正的熵惩罚项(x ln x - x + 1)构造熵正则化惩罚序列,并证明当温度参数λ→0时,该序列单调收敛到经典美式期权价值且在附加正则条件下给出显式收敛速率;同时设计基于线性BSDE的策略改进算法(PIA),并在Black–Scholes下的max-call数值实验中验证方法的数值稳定性与一致性
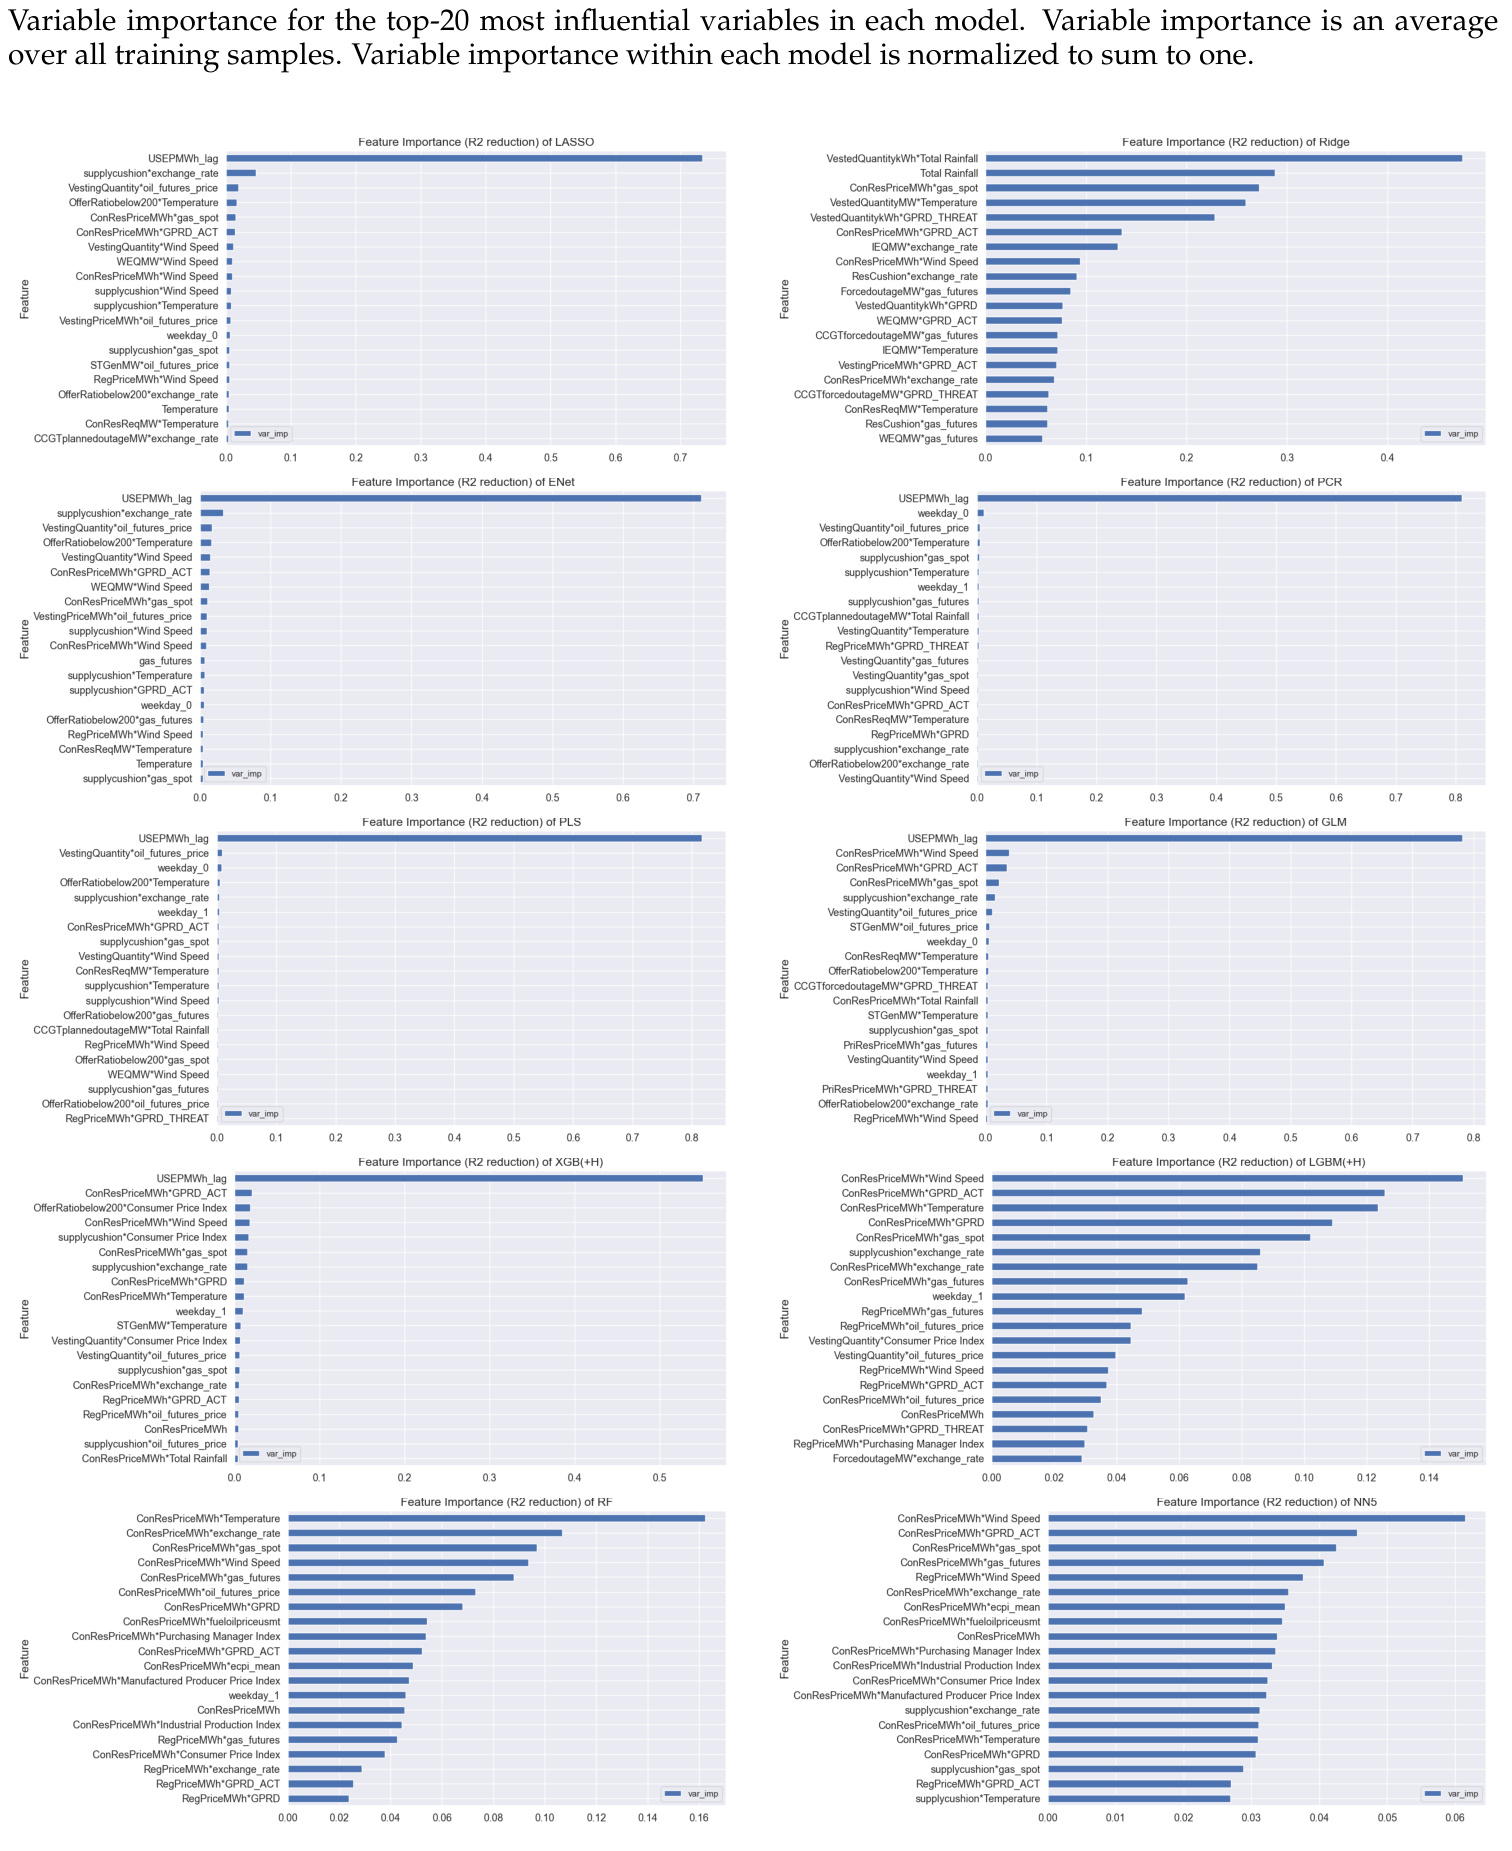
Electricity Market Predictability: Virtues of Machine Learning and Links to the Macroeconomy