CREDIT SPREADS’ TERM STRUCTURE: STOCHASTIC MODELING WITH CIR++ INTENSITY
发表于 2026年1月8日上传于 2026年1月9日
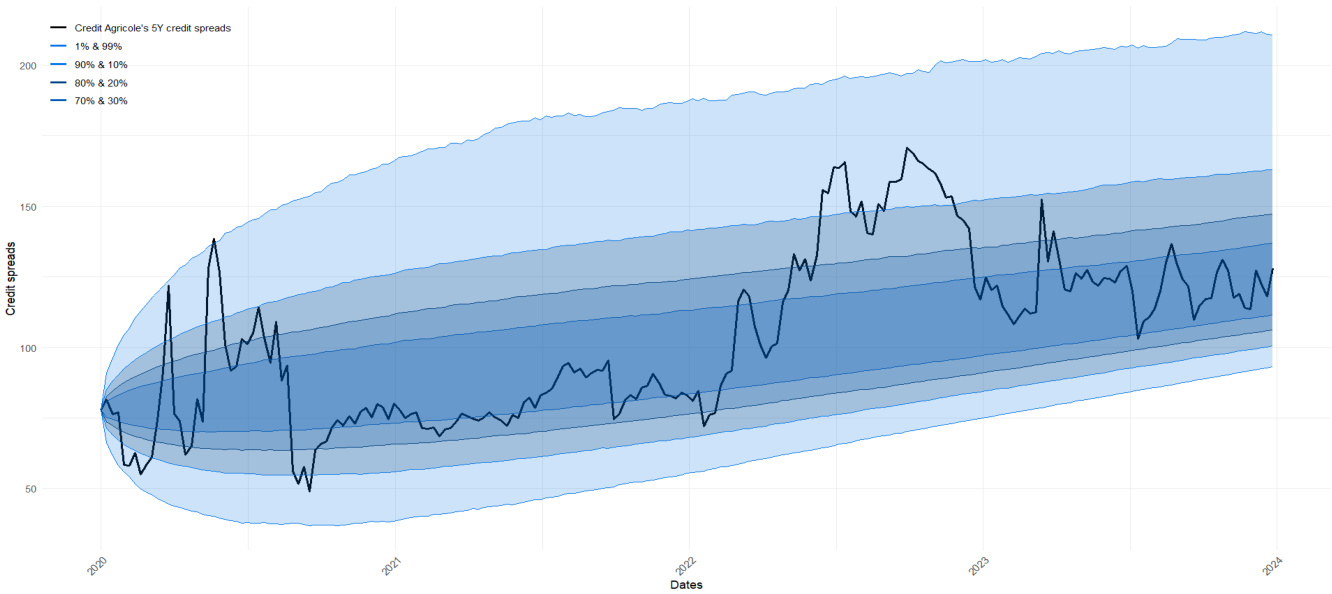
This paper develops a CIR++ intensity-based stochastic model that yields closed-form expressions for defaultable bond prices and the term structure of credit spreads, fits the initial market-implied survival curve, and provides an analytical credit-spread formula tractable for calibration and simulation. Calibration is performed by minimizing the Sum of Squared Relative Errors between historical and theoretical volatilities of the default intensity, and the model is validated by Monte‑Carlo diffusion and back-testing where extreme quantiles largely envelope historical spreads .