A Bipartite Graph Approach to U.S.-China Cross-Market Return Forecasting
发表于 2026年3月11日上传于 2026年3月12日
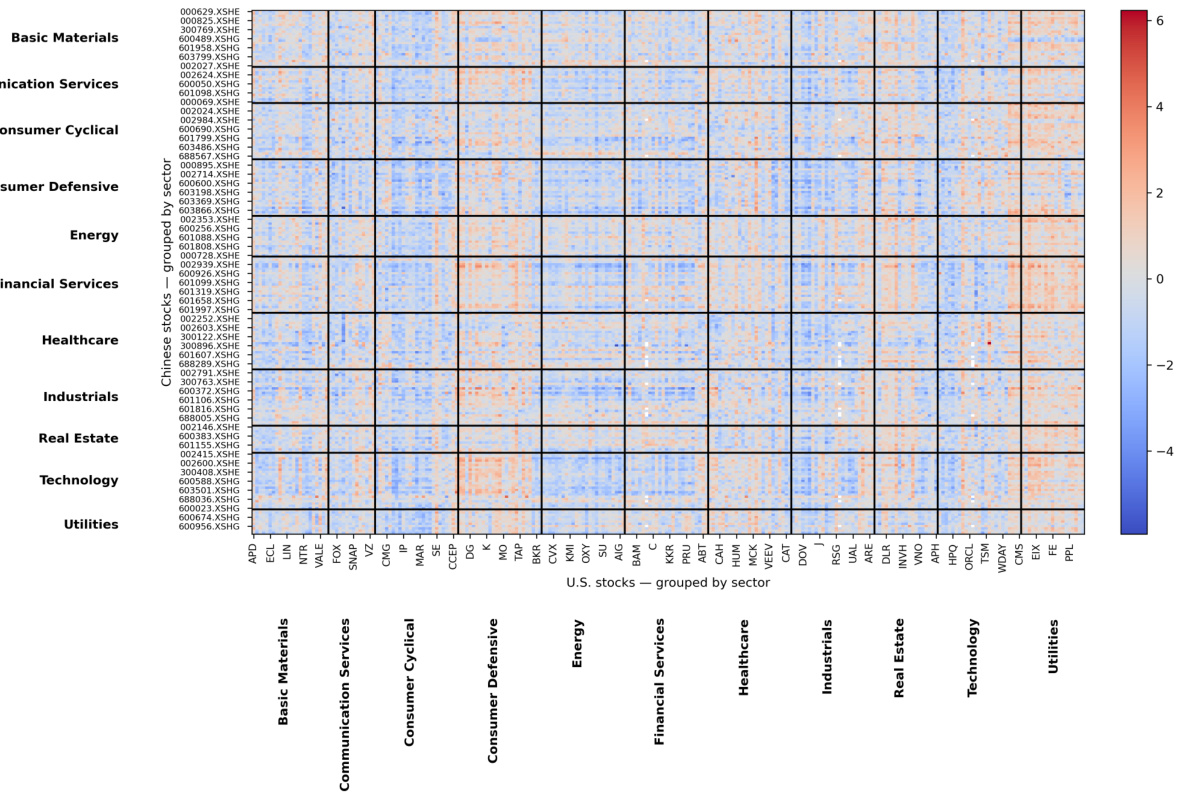
We propose a directed bipartite-graph framework that screens time-ordered cross-market predictors (via rolling-window t-statistic thresholding) and feeds the sparse graph-selected features into a suite of machine-learning models to forecast next-session open-to-close returns; the approach uncovers a pronounced directional asymmetry — U.S. previous-close-to-close information is substantially more predictive for Chinese intraday returns than the reverse — and combining graph-based selection with cross-market features materially improves out-of-sample Sharpe Ratios across many models .
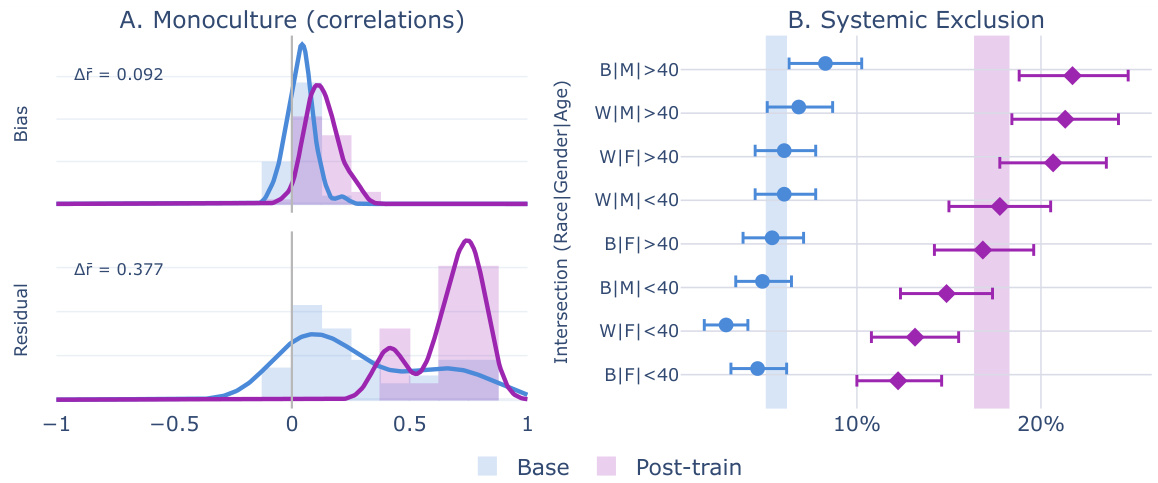
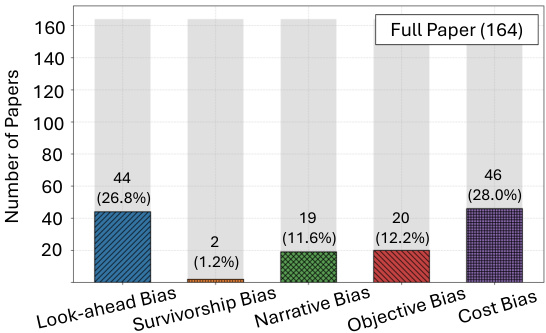
Evaluating LLMs in Finance Requires Explicit Bias Consideration
Needles in a haystack: using forensic network science to uncover insider trading
发表于 2025年12月21日上传于 2025年12月23日
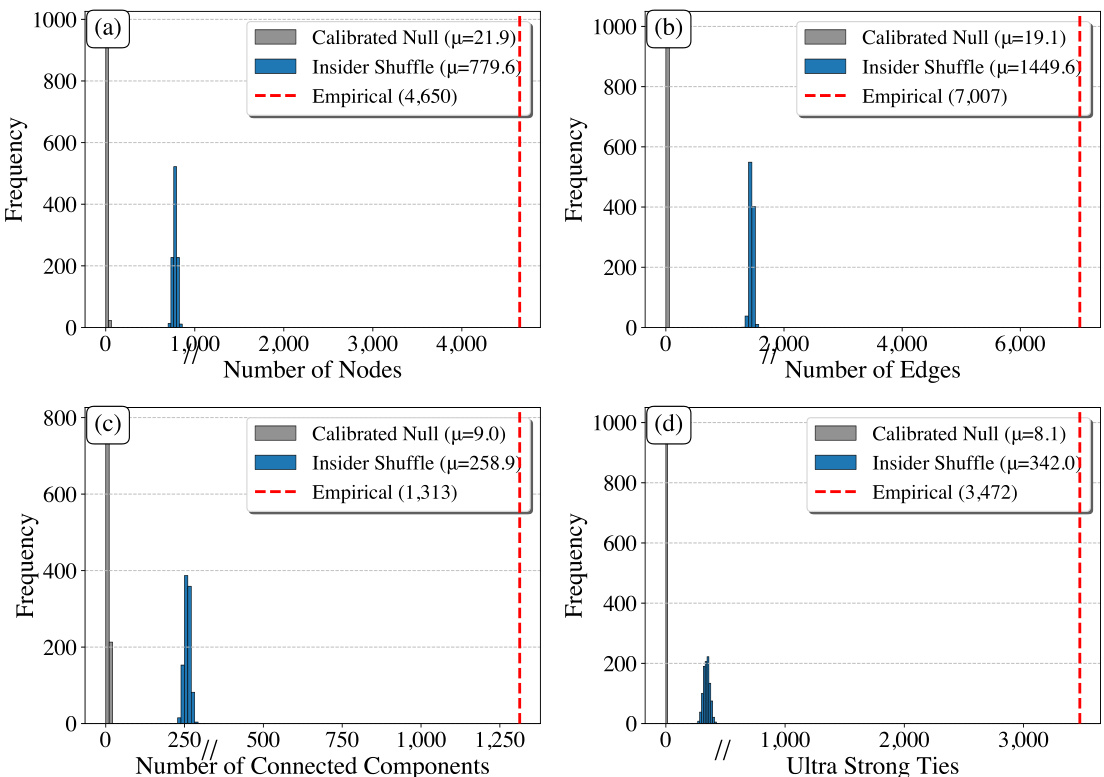
本文提出并验证了一种基于时间序列对齐的网络化筛查方法:以2014–2024年约2.9百万份SEC Form 4 报告为样本,构建了以“每周线性核”衡量交易时间相似性的内部人交易相似性网络,并通过两个严格的空模型(校准生成模型与受限时间置换)检验网络结构显著性,发现实证网络在节点数、边数与超强连边等指标上显著超出随机基线,表明存在统计上不易由监管窗口或共同市场事件解释的协调交易群体
Adaptive Partitioning and Learning for Stochastic Control of Diffusion Processes